Artificial intelligence is changing almost every industry, and insurance is no exception.
While most consumers think of AI as tools like ChatGPT, insurance companies have been using increasingly sophisticated technology behind the scenes for years. Today, AI is accelerating that transformation—affecting everything from how your home is evaluated and your auto rate is calculated to how claims are processed.
Some of these changes can make insurance faster, more accurate, and more convenient. But they also make understanding your coverage more important than ever.
Here are some of the biggest ways AI is changing personal insurance—and what consumers should know.
1. Insurance Companies Know More About Your Home Than Ever Before
It wasn’t that long ago that an insurance company relied heavily on the information provided on an application and, occasionally, a physical inspection of the property.
That’s changing quickly.
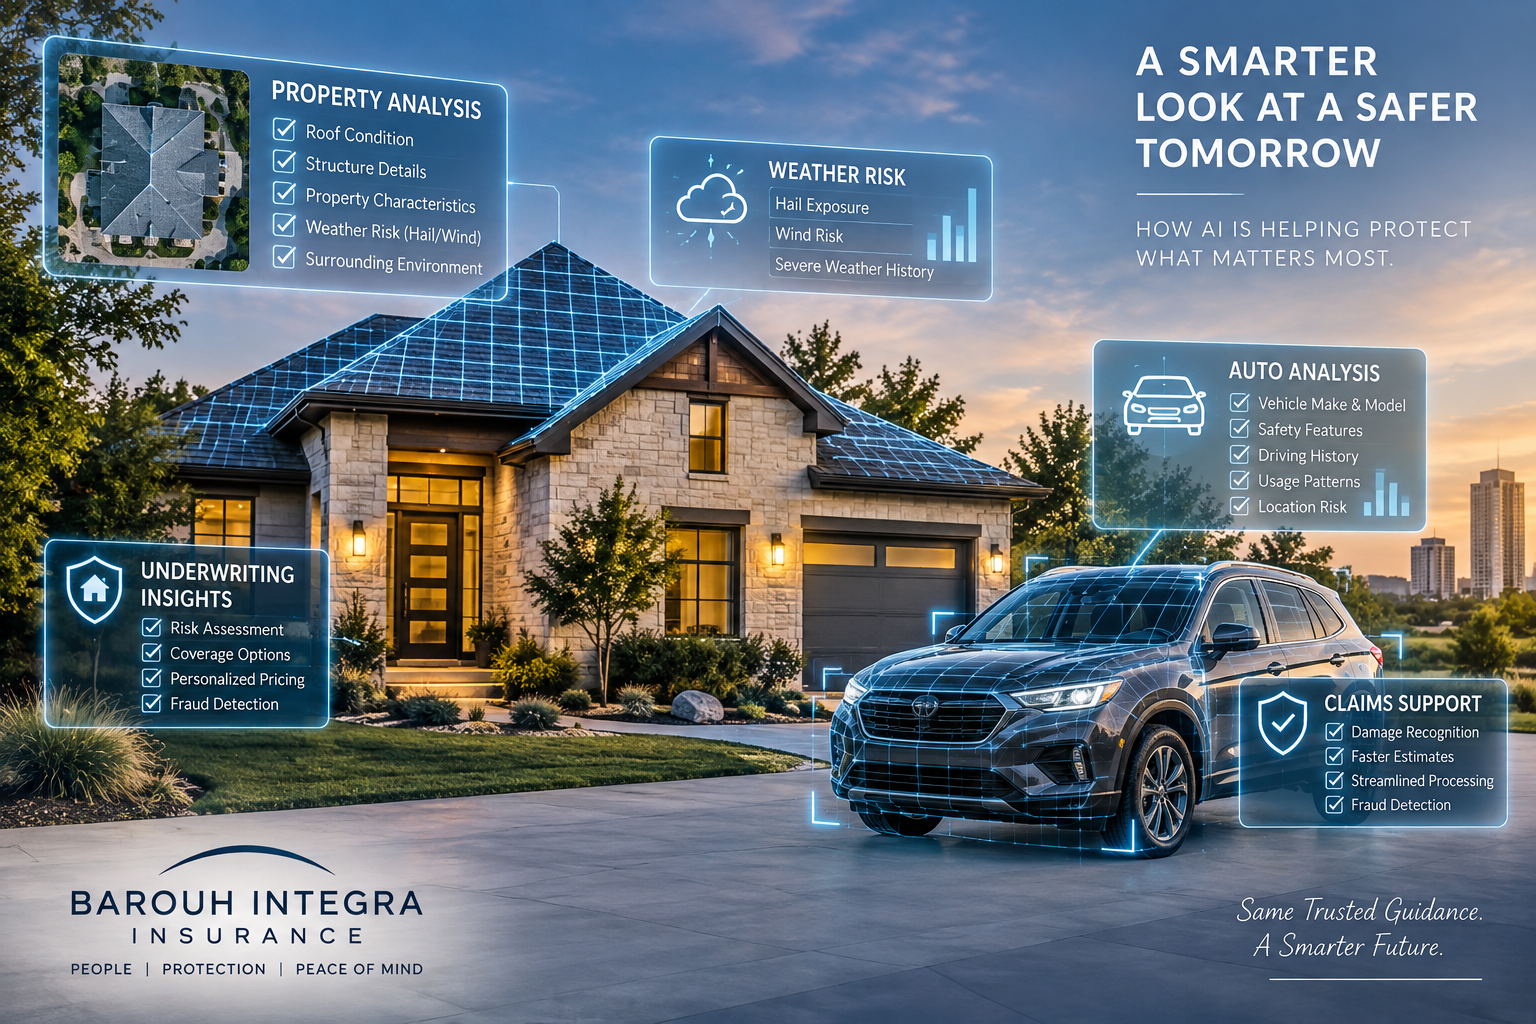
Insurers now have access to sophisticated property data, aerial and satellite imagery, building characteristics, historical weather information, public records, and other data sources. AI can help analyze that information and identify potential risks.
For homeowners, that can mean an insurance company may identify an aging roof, tree overhang, property condition issue, or other characteristic without ever sending an inspector to your house.
This technology can help insurance companies price risk more accurately, but it can also lead to additional underwriting questions, coverage restrictions, or even non-renewals when a property falls outside a carrier’s guidelines.
The days of an insurance company knowing very little about the property it insures are rapidly disappearing.
2. Home Insurance Is Becoming More Property-Specific
Two houses on the same street with similar values may increasingly receive very different insurance rates.
Why?
AI and predictive modeling allow insurers to evaluate hundreds of characteristics that may affect the probability or severity of a future claim.
Roof age and material, wildfire exposure, hail frequency, distance from emergency services, prior claims, construction characteristics, water-loss potential, and severe-weather patterns can all influence underwriting and pricing.
This is particularly important in areas like Texas and Colorado, where hail, wind, wildfire, and severe weather have created significant losses for insurance companies.
The result is a market where finding the right insurance company isn’t simply about finding the lowest advertised rate. Different carriers may evaluate the exact same property very differently.
3. Your Driving Data May Play a Bigger Role in Auto Insurance
AI is also changing how auto insurance companies evaluate drivers.
Traditional auto insurance pricing has relied on factors such as driving history, vehicle type, location, age, and insurance history. Today, telematics programs can provide insurers with information about actual driving behavior.
Depending on the program, this may include mileage, braking, acceleration, time of day, and other driving characteristics.
AI can analyze this information to help insurers differentiate between driving behaviors rather than relying entirely on traditional rating factors.
For safe drivers, this can create opportunities for discounts. It also represents a broader shift toward insurance pricing that is increasingly based on individualized data.
4. AI Could Make Insurance Claims Faster
One of the most promising applications of AI is claims handling.
For relatively straightforward claims, insurers can use technology to analyze photographs, identify vehicle damage, estimate repair costs, review documents, and detect potential fraud.
Instead of every claim moving through the exact same manual process, technology can help insurance companies identify simple claims that may be resolved more quickly while directing complicated claims to experienced adjusters.
That doesn’t mean human adjusters are disappearing.
Large property losses, liability claims, disputed damage, coverage questions, and complicated accidents still require judgment and investigation. AI may be very good at recognizing patterns, but insurance claims frequently involve circumstances that don’t fit neatly into a computer model.
5. AI Can Compare Prices. Can It Compare Coverage?
This may ultimately be one of the most important questions for consumers.
AI will undoubtedly make shopping for insurance easier. Consumers can already use AI tools to explain insurance terminology, research companies, and compare products.
But insurance isn’t a commodity.
Two homeowners policies with similar premiums can provide dramatically different protection.
One policy might provide replacement cost coverage on your roof while another uses a depreciated roof payment schedule. One might have a 1% wind and hail deductible while another has a 2% or 3% deductible.
Coverage for hidden water leaks, water backup, buried utility lines, foundation-related water damage, ordinance or law, extended replacement cost, and other exposures can also vary significantly between insurance companies.
The same issue exists with auto insurance.
Having “full coverage” doesn’t necessarily mean having adequate liability limits, uninsured motorist protection, rental reimbursement, replacement cost options, or an umbrella policy protecting your assets.
AI can help identify these differences—but only if someone knows which questions to ask.
6. The Role of the Independent Insurance Agent Is Changing
Technology will continue automating many of the administrative tasks historically associated with insurance.
We think that’s a good thing.
An independent insurance agency shouldn’t simply exist to produce quotes or issue insurance cards. Technology allows us to spend more time doing something much more valuable: helping clients understand risk and make informed decisions.
At Barouh Integra Insurance, our job is to look beyond the premium.
That means reviewing deductibles, coverage limitations, replacement costs, liability exposures, policy endorsements, and the financial strength and appetite of different insurance companies.
It also means periodically reviewing a client’s insurance portfolio as their life changes.
Buying another property, adding a teenage driver, purchasing a new vehicle, renovating a home, starting a business, or accumulating additional assets can all change someone’s insurance needs.
AI can process an extraordinary amount of information. But understanding how those pieces fit together for an individual or family still requires context.
7. The Future of Insurance May Actually Be More Personal
There’s an interesting irony in all of this.
As insurance companies become increasingly automated, having a knowledgeable human adviser may become even more valuable.
Algorithms will become better at evaluating risk. Claims will become faster. Quoting will become easier. Consumers will have more information available than ever before.
But more information doesn’t necessarily make insurance simpler.
In many ways, personal insurance is becoming more complicated as carriers introduce new deductibles, exclusions, roof settlement schedules, underwriting requirements, and coverage options.
The goal shouldn’t simply be to use technology to find the cheapest policy.
It should be to use technology to make better insurance decisions.
Let Technology Do the Math. Let Us Help With the Insurance.
At Barouh Integra Insurance, we embrace technology—including AI—when it helps us serve our clients better. But we also believe technology works best when it’s paired with experienced advice.
As an independent agency, we can compare multiple insurance companies, help explain the differences between policies, and identify potential gaps that may not be obvious from a quote alone.
Whether you’re reviewing your homeowners insurance, auto insurance, umbrella coverage, rental properties, or your entire personal insurance portfolio, we’re happy to take a second look.
Want to know how your current coverage compares? Contact Barouh Integra Insurance for a personal insurance review. We’ll help you understand what you’re paying for, where potential gaps may exist, and whether there are better options available.